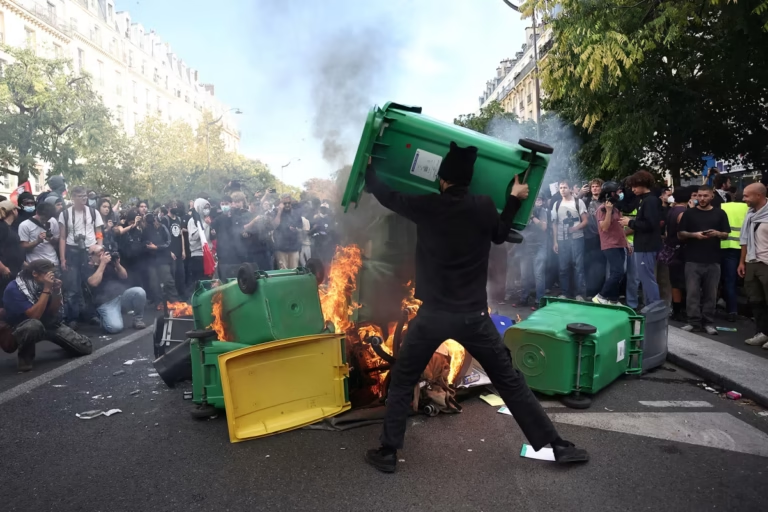
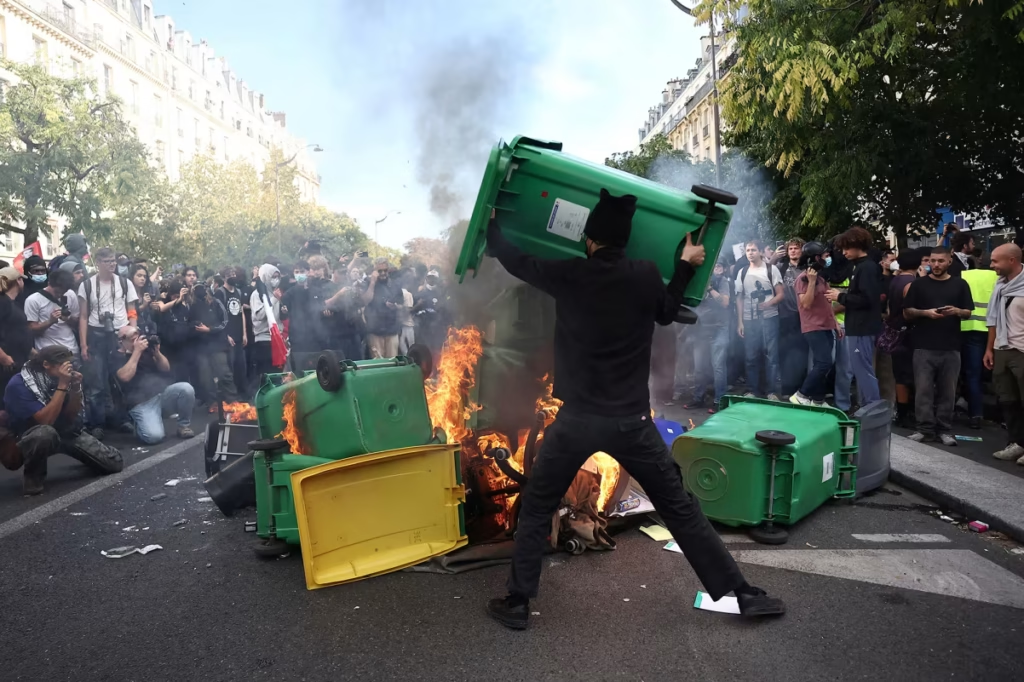
France’s unprecedented wave of student protests has laid bare the country’s growing financial pressures, which will only become more difficult to tackle as Europe’s second-largest economy tries to rein in a ballooning budget deficit.
The country’s finances are in a precarious state. Public debt was more than $4 trillion in June, exceeding the size of the economy, according to the country’s statistics agency. The cost of servicing that debt has climbed by billions of dollars on last year, as bond yields spike. At the same time, demands on the public purse are rising: Pension costs have climbed because of an aging population while the government looks to spend more on defense.
High school students, meanwhile, have called for a fix to staff shortages, overcrowded classrooms and crumbling school infrastructure. Solutions to France’s financial troubles have led to social unrest in the past. Efforts to raise the retirement age sparked widespread protests in 2023.
Last week, the French government proposed deep spending cuts and tax hikes aimed at narrowing the budget deficit, but bond buyers are concerned that fiscal measures may be watered down by lawmakers ahead of presidential elections next year, said Andrew Kenningham, chief European economist at consultancy Capital Economics.
The election could see President Emmanuel Macron ousted by either a far-right or far-left successor, raising questions over the country’s commitment to fiscal discipline. While Marine Le Pen’s right-wing National Rally recently proposed substantial spending cuts meant to stabilize the public finances, her party also remains committed to costly tax reductions, Kenningham said.
“Investors will also be concerned about greater fiscal populism after the elections,” he wrote in a note last week. “There is a big risk that spreads rise a lot further, either before or after next year’s elections.”